Property Damage Claims Process: 9 Steps to Getting Paid Fast
What Is the Property Damage Claims Process?
TL;DR: Call it in early, take too many photos, watch your deadlines and question every estimate. Think of it as the stretch of road between “oh no” and “okay, the check cleared.” A pipe gives out at 2 a.m. Hail shreds the shingles on a Tuesday afternoon. Somebody forgets a pan on the stove. What follows is a long string of calls, photos, inspections and paperwork.
And it isn’t rare. Line up 35 insured homes and the Insurance Information Institute figures about one of them will have a wind or hail claim; for water damage or freezing, it’s closer to one in 60. We’ve watched a lot of these claims up close, and the smooth ones almost always share one thing: somebody knew the steps before the adjuster showed up.
Who’s Who in Your Claim
This is the part we wish every homeowner heard on day one. The adjuster drinking coffee on your porch is probably very nice, and the insurance company signs their paycheck. Nothing sinister about it. It just helps to know who’s on which team.
- You. The policyholder. Your name is on the policy, so you open the claim.
- The company adjuster. Sometimes they visit in person, sometimes they work from a desk. Either way, the insurer pays them.
- An independent adjuster. Extra help the insurer brings in when a storm buries them in claims. Same team as the company adjuster.
- A public adjuster. The only adjuster who works for you. Licensed by the state and usually paid a cut of the settlement.
- Your contractor. The crew drying, tearing out and rebuilding. They also tend to catch what the first estimate missed.
- A claims attorney. Hopefully you never need one. But if coverage gets denied or the insurer starts stalling for no good reason, that’s who you call.
The Property Damage Claims Process, Step by Step
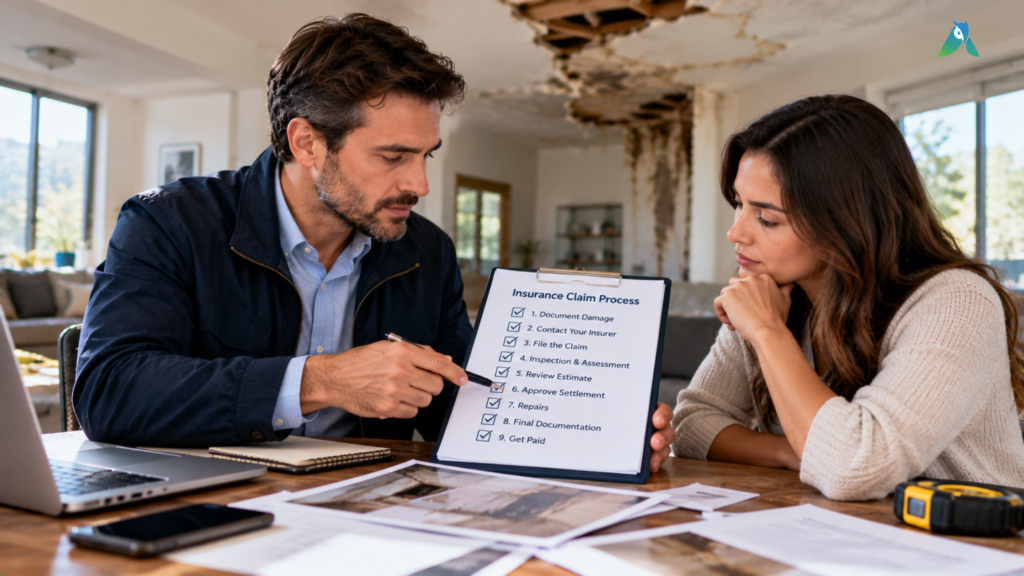
No two claims look exactly alike. Still, almost every one we’ve seen follows this order.
Step 1: Stop the Damage From Getting Worse
Once everyone’s safe, your policy expects you to keep things from getting worse. Shut the water off at the main. Throw a tarp over the hole in the roof. Nail some plywood over that busted window.
Grab your phone before you touch anything, though, and keep every receipt, even the $14 one from the hardware store. Insurers usually pay for reasonable emergency work. Mold that showed up because the carpet stayed soggy for two weeks? That’s a much harder sell.
Step 2: Pick Up the Phone (or Log In)
Don’t sit on it. Call or file online the same day if you can, and give them the basics: when it happened, what caused it, which rooms or parts of the roof got hit, and anything you’ve already done to stop it. One small habit saves a lot of grief later, too. Ask for the claim number and the adjuster’s name in an email, not just over the phone.
That call also starts a clock for the insurer. Texas is a good example. According to the Office of Public Insurance Counsel, the company gets 15 days to acknowledge the claim and get its investigation going, and after a weather catastrophe declared by the Texas Department of Insurance, add another 15 days on top.
Step 3: Actually Read Your Policy
Nobody wants to. Do it anyway, at least the declarations page, because fifteen minutes now can save you weeks of arguing later. Look for:
- How big your deductible is, and whether wind or hail has its own (often a percentage, which stings)
- What the policy pays for the house, the shed and fence, your stuff, and a hotel if you can’t stay home
- What’s excluded, with flood being the classic surprise
- Whether you owe them a sworn proof of loss, and by when
Some of these policies run 60 pages of legalese. If you’d honestly rather skip the reading, Adjusted’s AI Policy Analyzer will pull the coverages, exclusions and deadlines out for you.
Step 4: Document Like You’ll Need It in Court
You probably won’t end up in court. Document like you might. Go room by room: the wide shot, then the close up, then a slow video where you narrate what you see, like you’re giving a tour to someone who’s never been inside. After that, jot down what got ruined, about how old it was, and what a replacement costs today.
Keep a running claim log too. Nothing fancy, a notes app works fine. Every call, every email, who said what and when. Somewhere around month three, someone will say “we never received that,” and you’ll want the receipts.
Step 5: Show Up for the Inspection
Be home for this one. Walk the adjuster through every spot the damage reached, attic and crawl space included, plus anything new you’ve noticed since that first call. If your contractor can make it, even better.
And don’t agree to a number standing in the driveway. Ask for the estimate in writing and read it later at the kitchen table.
Step 6: Check the Estimate Line by Line
Nine times out of ten, the insurer’s estimate comes out of Xactimate, and the total at the bottom is the least useful number on it. The line items are where money goes missing. Put it next to your contractor’s estimate and go row by row. We see the same misses over and over:
- Drip edge, underlayment, or detach and reset work that never made it onto the page
- Roof squares or drywall that somehow measured smaller than reality
- Zero overhead and profit on a job that clearly needs three or four trades
- Code upgrades the city will make you do anyway
Doing this by hand is a slog, easily a couple of hours per claim. That’s why we built our Estimate Analyzer: drop in the original and the supplement, and the differences show up side by side in a few minutes.
Step 7: Don’t Panic During the Investigation
The larger the claim, the more the insurer wants to know. Expect a recorded statement, maybe a sworn proof of loss, and every so often an examination under oath. Some folks also get a reservation of rights letter in the mail around now.
People panic when that letter shows up. Please don’t. It isn’t a denial; it’s the insurer saying, in legal language, “we’re still checking, so no promises yet.” Reply by the deadline, keep your answers factual, and if the letter starts quoting specific exclusions, that’s a good moment to loop in a public adjuster or an attorney.
Step 8: Get Paid (Usually in Two Checks)
Here’s the part that trips up nearly every homeowner we talk to. Replacement cost policies usually pay in two rounds. Round one is actual cash value, meaning what the damaged property was worth after depreciation, minus your deductible. Round two is the depreciation they held back, and you only see it once the work is done and invoiced. On a fairly typical roof and interior claim, it looks like this:
| Payment item | Amount |
| Replacement cost estimate | $28,000 |
| Your deductible | $2,500 |
| Depreciation held back | $7,000 |
| First check (actual cash value less deductible) | $18,500 |
| Second check after repairs are finished | $7,000 |
| Total paid by the insurer | $25,500 |
If you’ve got a mortgage, your lender’s name will probably be on the check as well. Call the servicer early and ask how they release repair money, because some take weeks and your roofer won’t love that.
Step 9: Supplement, Then Close It Out
Once the crew starts tearing things open, surprises are pretty much guaranteed. Rotten decking under the shingles. Insulation still wet behind the drywall. None of that means anyone messed up. You simply send a supplement with fresh photos, an updated estimate and a short note on what turned up.
Keep one eye on the calendar, though. Under Florida Statute 627.70132, you get one year from the date of loss to report a new or reopened claim, and 18 months for a supplemental one. And don’t let anybody close the file until every supplement and every depreciation check has actually landed.
So How Long Does Property Damage Claims Process Take?
A small water claim might be wrapped up in a few weeks. A big storm loss with a fight over the scope? That can stretch into months. State law keeps insurers moving, though. In Texas, once they have everything they asked for, they get 15 business days to say yes or no and 5 business days to pay. In Florida, insurers generally have 60 days from notice to pay or deny.
For what it’s worth, the industry does seem to be improving. In the J.D. Power 2026 U.S. Property Claims Satisfaction Study, homeowner satisfaction jumped 20 points, landing at 702 on a 1,000 point scale. The two biggest drivers? A fair settlement and trust. Speed matters, but feeling treated fairly matters more.
When the Offer Is Low or the Claim Gets Denied
First, read the reason. A denial letter has to tell you why, and that reason is basically a list of what you need to disprove. From there, go one step at a time:
- Ask for a reinspection and send your contractor’s estimate
- File a supplement for anything that was missed
- Use the appraisal clause if you only disagree about the amount
- Complain to your state department of insurance
- Call a claims attorney if things start to look like bad faith
Appraisal is the step people forget exists. You pick an appraiser, the insurance company picks theirs, and those two agree on a neutral umpire. When any two of the three land on a number, that’s the number, and in our experience it’s usually faster (and a lot cheaper) than heading to court.
If You Handle Claims for a Living
Now flip the view. If you’re a public adjuster, contractor or attorney, you’re not juggling one claim. You’re juggling fifty, maybe five hundred. The nine steps aren’t the hard part. The hard part is the supplement stuck in somebody’s inbox, the photos scattered across three phones, and the deadline that quietly slipped by during hurricane season. Most CRMs were designed to track sales deals, and you feel it the minute you try to run a claim through one.
We built Adjusted for exactly that mess. Each claim lives in one record holding the policy, photos, estimates, supplements, deadlines and billing, all protected by SOC 2 Type II certified security. Still shopping around? Our guide to insurance technology solutions for claims teams covers what’s actually worth paying for.
FAQs
How do property damage claims process work?
You report it, keep the damage from spreading, and document everything you can. The insurer sends an adjuster, who looks it over and writes an estimate. You get paid for what the policy covers, minus the deductible, and if the repair crew finds more, you file a supplement.
How long does an insurance company have to pay a claim?
That depends on where you live. In Texas, once a claim is accepted, the insurer has 5 business days to pay. Florida insurers generally get 60 days from notice to either pay or deny.
What is recoverable depreciation?
Think of it as money the insurer parks on the side. On a replacement cost policy, they hold it back from the first check and release it after repairs are finished and you send proof, usually the final invoices.
Should I hire a public adjuster?
For a small, simple claim, probably not. For a big one, or one where the first offer made you wince, it’s worth a call. Public adjusters work for you, not the insurer, and they usually take a percentage of what they recover.
Bottom Line
Every claim walks the same nine steps. What decides the size of the final check is how well each step got documented. Skip one line item or miss one deadline, and that money just stays on the insurer’s side of the table.
Done chasing paperwork through inboxes and spreadsheets? Grab a free Adjusted demo and see what claims feel like when everything finally lives in one place.
