How Your Firm Can Put AI Insurance Claims Processing to Work
So, What Is AI Insurance Claims Processing?
TL;DR: Insurers already use AI on your claims. If you work the policyholder’s side, you should too. Think of it as a very fast reader that never gets bored of claim files. With AI insurance claims processing, you hand over the policy, the estimate, the photos and the carrier’s letters, and it points you to the parts that deserve your attention. A good chunk of this isn’t new, since searching a scanned PDF has been possible for years. The newer part is software that actually understands what a sentence in a policy means.
Most of the marketing is aimed at carriers, and honestly, that’s where the money is. EY surveyed US insurers and found they were counting on AI to cut costs by more than 20% on average within two years. You won’t find many articles like that written for the adjuster on the other side of the claim. So let’s change that.
Are Insurers Using AI to Process and Deny Claims?
They are, and more of them every year. According to NAIC survey numbers, 88% of private passenger auto insurers and 70% of homeowners carriers either use AI already or are looking into it. On a typical file, that software sorts the claim, gives it a fraud score, boils the documents down to a summary and nudges the desk adjuster toward a next step.
Regulators have noticed. Back in December 2023 the NAIC put out a model bulletin about how carriers use AI, and by mid 2026 about 25 states had signed on. Florida went a step further. HB 527 says a real person with authority has to look at a denial or a reduced payment before it goes out, so nobody gets turned down just because a program said so. For you, that’s good news. Carriers now have to explain themselves on paper, and your own file should be at least that tidy when you challenge them.
How AI Insurance Claims Processing Works on Your Files
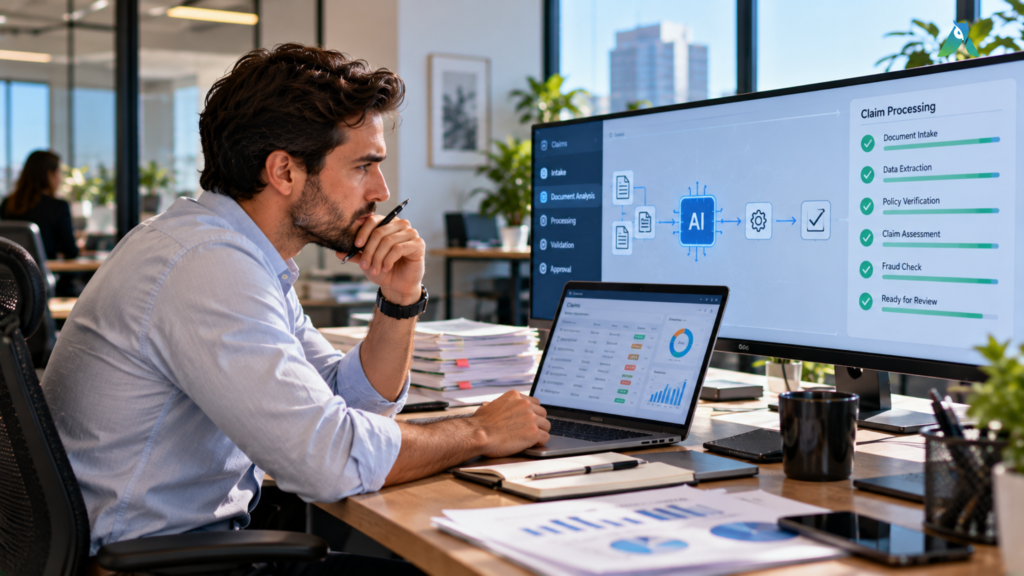
Here’s what it looks like once you start running your own claims through it. Nothing fancy happens. Each step just takes one annoying chore off your plate.
Step 1: Getting Everything Into One Place
Most claims start as a mess. The policy is in one email, the photos are on somebody’s phone, and the estimate is buried in a shared folder. You drop all of it in, and the software sorts it into a single claim record. It also grabs the basics for you, like the date of loss, the policy number, and the limits.
That alone saves more time than people expect. Just ask anyone who has spent twenty minutes hunting for a signed proof of loss.
Step 2: Let It Read the Policy First
Nobody enjoys reading a 60 page policy, and the clause that matters is never near the front. The AI goes through the declarations, exclusions and endorsements and tells you which ones touch this particular loss. Adjusted’s Policy Analyzer gets it done in a few minutes, which is handy when you want to spot an ordinance and law endorsement before your first letter goes out.
Step 3: Comparing Estimates
This is where the money is. The software lines up the carrier’s estimate against yours and shows you what got removed, trimmed, or repriced. No more squinting at two PDFs side by side.
Our Estimate Analyzer reads Xactimate files directly. One of our users told us variance reports used to eat half his day. Now he gets them almost instantly.
Step 4: Finding the Right Photo
A big loss can come with thousands of photos, most of them named something like IMG_4471. You don’t scroll. You type something like “water stain by the north window” and the right shots pop up.
Step 5: Keeping Deadlines and Invoices Straight
The boring stuff matters too. Deadlines, follow ups, and carrier letters stay attached to the claim, so a busy storm season doesn’t bury a due date. Invoices, hours, and liens live in the same file, which makes getting paid at the end a lot less painful.
Carrier AI vs. Claimant AI: Same Tech, Different Job
Both sides use similar tools. They just want very different things out of them.
| On the carrier’s side | On your side | |
| What it’s for | Cutting claim costs and moving simple claims fast | Getting the policyholder everything they’re owed |
| Who uses it | Desk adjusters, fraud units, claims managers | Public adjusters, contractors, claims attorneys |
| What it does most | Sorts claims, scores fraud risk, auto approves easy ones | Reads policies, compares estimates, keeps the file tight |
| What it reads | Claim forms, call notes, internal data | Policies, Xactimate estimates, photos, letters |
| How they score a win | Lower cost per claim | A faster, fuller settlement that holds up |
And the generic CRM a lot of firms still use? It doesn’t fit either column. It was built to push sales leads through a pipeline. Ask it to read an Xactimate estimate and you’ll be waiting a long time.
What This Looks Like Day to Day
Same software, different payoff. It really comes down to what kind of work fills your week.
For Public Adjusters
- Get through the whole policy before you pull into the driveway for the inspection.
- Put supplements together faster because the variance report is already done.
- Stop forwarding emails to yourself, since notes, photos, and letters stay with the claim.
- Take on more files after a big storm without hiring another office person right away.
For Restoration Contractors
You already live in Xactimate, so the win here is catching line items that slipped through and knowing which supplements are still stuck. It also helps to see, in one spot, which jobs still owe you money or have a lien hanging open.
For Claims Attorneys
Law firms get the file handed over already in order. Every document, date and letter sits where it should, so piecing together how the carrier handled the claim takes far less digging.
If you want to see what else is out there, we wrote a separate guide on insurance technology solutions for claims teams that covers the rest.
Where AI Still Gets It Wrong
Let’s be honest about the limits. AI can misread a fuzzy scan, and it has no idea the roof decking felt soft underfoot unless someone writes that down. It’s a fast reader, not a licensed adjuster. A person should always check its output before anything goes to the carrier.
Funny enough, the insurance industry says the same thing. At a Florida House hearing that Insurance Journal covered, a spokesman for the mutual insurers’ trade group said that if a person isn’t allowed to do something, AI isn’t either. We agree. Let the software do the reading, and keep the judgment calls for yourself.
How to Pick AI Claims Processing Software
Plenty of products slap “AI” on the box these days. Before you sit through a single demo, have these questions ready.
- Was it made for claims? If the main screen looks like a sales pipeline, keep looking.
- Can it open Xactimate files? If it can’t, you’ll still be retyping estimates by hand.
- How does it protect client data? Ask to see a SOC 2 Type II report. We have one, and any serious vendor should.
- Can you check its work? You want to click a detail and see the exact page it came from.
- Is billing part of the claim? Invoices and liens shouldn’t live in some separate app.
- Will they help you move over? Moving off spreadsheets or an old CRM on your own gets ugly fast.
Got a claim on your desk right now? Book a demo and bring it with you. We’ll walk it through policy review, estimate comparison and billing live, on your file instead of a canned sample.
FAQs About AI Insurance Claims Processing
Are carriers using AI to deny claims?
A lot of them use it to review and score claims, yes. Some states are pushing back, though. In Florida, HB 527 says a qualified person has to review any denial or reduced payment.
Can AI read Xactimate estimates?
Some tools can. With Adjusted, you upload both Xactimate versions and it lays out every line that was added, cut or repriced.
Will AI replace public adjusters?
We really don’t think so. Someone still has to walk the property, negotiate with the carrier, and talk a stressed homeowner through the process. AI just cuts the paperwork so there’s more time for that part.
Is it safe to put client files in AI claims software?
It can be, but don’t take a vendor’s word for it. Ask for their SOC 2 Type II report and find out exactly who can see your data.
Can AI read a policy accurately?
Mostly, yes. It’s good at finding the right clause fast. Blurry scans still throw it off now and then, so check anything you plan to quote back to the carrier.
How long does an insurance company have to process a claim?
Every state is different. Most have prompt payment laws that give carriers a set number of days to acknowledge, investigate and pay. If those dates live in your claim software, it’s a lot easier to call a carrier out when they blow past one.
The Carrier Stopped Reading by Hand. Why Haven’t You?
Insurers made this move a while ago. Every hour you spend flipping between PDFs is an hour they’ve already saved. The good news is that the same kind of tools are open to you now, and some are built around how your work actually goes.
Bring us one claim. We’ll show you what changes. Schedule your Adjusted demo and watch AI insurance claims processing work on a file you already know inside out.
