Insurance Software Development: Should You Build or Buy Now?
What Is Insurance Software Development?
TL;DR: Honestly, most claims firms should buy software, because building costs more and takes far longer. Strip away the jargon and insurance software development just means getting software made for insurance work. Claims tracking, invoicing, a portal your clients can log into. So who makes it? You can hire developers to build it from scratch. Or you can pay a vendor who already built it and sells it to plenty of firms like yours.
Type the phrase into Google and something looks off right away. Nearly every result is a development agency chasing big insurance carriers, not a ten person adjusting shop. If that’s you, or you run a restoration company or a claims law practice, those pages weren’t written with you in mind. Our post on policy administration vs claims management software explains why the two worlds don’t overlap much, so start there if the terms feel blurry.
Two Kinds of Insurance Software
- Policy administration software is the carrier side. Quotes, renewals, cancellations.
- Claims management software picks up after a loss: files, estimates, documents, billing.
- Custom software can be either one, built from scratch for a single company.
Why Claims Teams Think About Building
Picture a 12 person adjusting firm right after hail season. Emails are spread across six inboxes. Photos live on people’s phones. Someone is comparing a carrier estimate to a contractor’s estimate line by line, and it’s already 4 p.m. One supplement review eats the afternoon, and forty more files are waiting.
That’s when somebody says, “Why don’t we just build our own?” We get it, and sometimes that really is the right call. But most of the time the real problem has a cheaper fix, and we’ll walk through it below.
Where It Usually Hurts
• Claim files split across email, shared drives, spreadsheets, and phones
• Comparing a carrier estimate to a supplement by hand, often in Xactimate
• Policy language that’s dense and easy to misread when a deadline is breathing down your neck
• Invoices, time, and liens living in some other tool
• Variance reports that take half a day to build
What Building Custom Insurance Software Really Takes
So what does a build actually involve? Quite a bit more than somebody typing code. You need discovery, design, development, testing, security work, data migration, training, and support for as long as you keep the thing. Development shops publish their own prices, which is handy, so we’ll lean on theirs. ScienceSoft’s own page puts an average mobile insurance app at around $120,000. The big AI heavy systems can run a million or more, and even a first working version takes three months at the very least. Appinventiv paints a similar picture, with simple builds taking 3 to 6 months and the complicated ones dragging past a year.
Money isn’t the only cost. McKinsey’s case study on Aviva’s claims AI work describes a team of more than 50 data scientists, engineers, business leaders, and change specialists. A claims firm won’t need an army like that, but notice that business leaders and change specialists were on the team too, not only engineers.
The Stuff Nobody Puts in the Quote
- Upkeep never stops. Even if you add zero features, somebody has to patch security holes and fix bugs every year.
- Integrations. Email, calendars, accounting, estimating files. Each one is its own mini project.
- Moving old claim files in. It’s slower and messier than anyone plans for.
- A security review the day a client asks where their data lives.
- One developer leaving, and nobody else understands the code.
Build vs Buy: A Side by Side Look
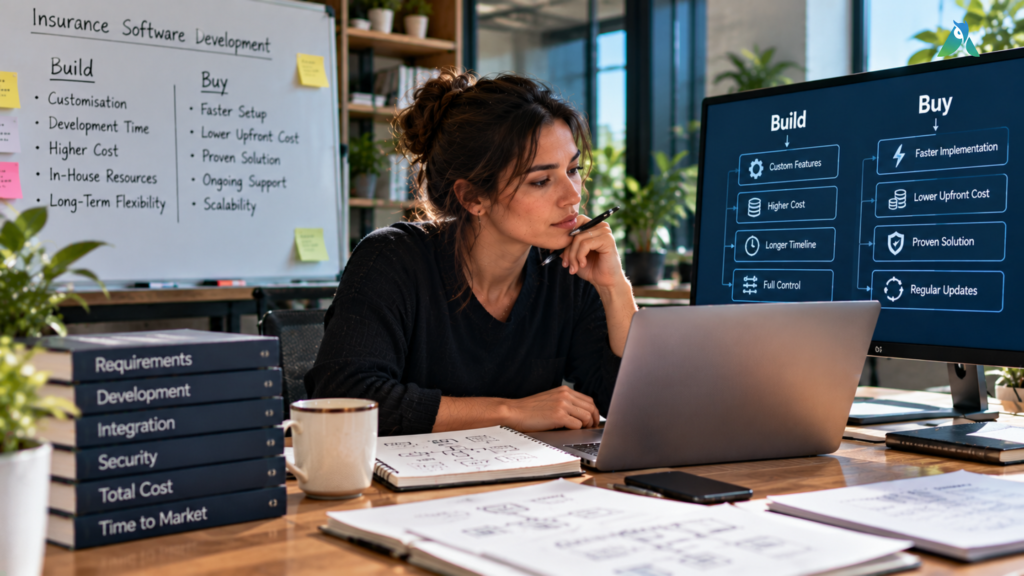
Here’s how the two paths stack up for a typical claims firm.
| Factor | Build Custom | Buy Purpose Built |
| Time to start | Months to over a year | Days to weeks |
| Upfront cost | High | Lower, usually a subscription |
| Ongoing upkeep | Your team or a contractor | The vendor handles it |
| Claims know how | You teach developers your process | Already built into the product |
| Fit for your workflow | Exact, if you specify it well | Strong for common claims work |
| Security proof | You earn it yourself | Vendor audits and reports |
| Risk if it goes wrong | You carry all of it | Shared, often with a trial |
| Best for | Unusual workflows | Most claims firms |
When Building Makes Sense
Building isn’t always the wrong move. If your process is truly odd and nothing on the market comes close, go for it. Same if you want to sell the software as a product of your own, or you already have engineers on staff who’ll still be looking after it in five years.
Here’s a gut check. Write down what you need that no product can do. If it’s a couple of small things, you’re buying. If it’s basically the whole reason clients hire you, building deserves a serious look.
When Buying Is the Smarter Move
For most claims teams the shopping list is short and a little boring: files, documents, estimates, tasks, billing, reports. All in one place. A claims management platform made for that work gets you running sooner, and the vendor deals with updates, upkeep, and security so you don’t lose weekends to it.
You can also test before you commit, which is impossible with software that doesn’t exist yet. Run a single real claim through a trial. A week of that will teach you more than any proposal.
Questions to Ask Any Vendor
• Was it built for claims, or is it a generic CRM wearing a new label?
• Does it read Xactimate files, or will we retype numbers?
• Who moves our current files in, and how long does it take?
• If we leave, what happens to our data?
• What does support look like six months after launch?
What Good Claims Software Should Do
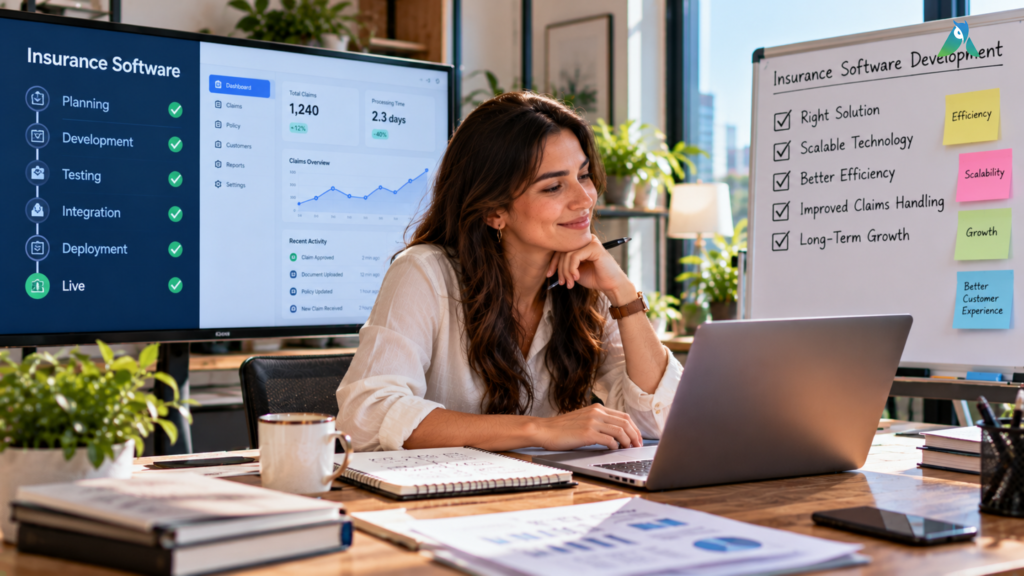
A decent claims tool keeps one record per claim, and everything lands in it. Emails, photos, estimates, notes. No more digging through six inboxes for that one message. It should also understand the paperwork, meaning it knows an estimate from a supplement from a policy, instead of treating them all as anonymous files.
One Adjusted customer says variance reports that used to take half a day now arrive instantly. That’s the bar for any demo you sit through. Are you getting real hours back, or just a nice looking screen?
Your Demo Checklist
• Every email, task, note, photo, estimate, and supplement landing in the claim it belongs to
• Estimate comparison that reads Xactimate files and checks the original against the supplement line by line
• Policy review that flags coverage and exclusions
• Invoices, time, expenses, and liens tied to the claim
• Reports in minutes, not hours
How AI Changes the Decision
AI is the reason plenty of firms start dreaming about building their own tools. It’s also a decent reason to buy. Training and maintaining AI takes specialist skills, and regulators are paying attention. The NAIC’s model bulletin on AI systems expects insurers to do due diligence on the third party AI they rely on, so put the same questions to any vendor: how does the AI work, and where does my data go?
The useful tools already exist. Take estimate comparison. A good tool reads the original estimate and the supplement and lines them up item by item, so what used to eat your afternoon takes a few minutes. Check its output anyway. It’s a fast assistant, and the final call still belongs to you.
Security and Compliance Questions to Ask
Think about what sits in a claim file: names, addresses, policy numbers, photos of people’s damaged homes. That’s private stuff, so security can’t wait until later. Whether you build or buy, you should be able to say who can open a file, where it’s stored, and how every access gets logged.
The easiest proof is a SOC 2 Type II report, so ask for one. It means an independent CPA firm tested the vendor’s controls against AICPA standards over a stretch of time, and not just on one lucky afternoon. Build your own and that testing lands on your plate, which is a cost lots of teams forget.
Do the Math Before You Decide
Before you compare anything, work out what the problem costs you today. Take the hours your team loses each week, multiply by 52, then by what an hour of their time is worth. Say 5 people each lose 4 hours a week at $50 an hour. That’s 5 times 4 times 52 times 50, or $52,000 a year. Gone, every year, on busywork.
Hold that number up against a build quote plus three years of upkeep, and against a software subscription. The cheapest option usually isn’t the one with the smallest price tag, so count everything.
Try Any Tool for One Week
- Day 1: Load one real claim, emails and photos and estimates included.
- Day 2: Run an estimate comparison on a file you’ve already reviewed yourself. Did it catch what you caught?
- Day 3: Ask the policy tool a coverage question where you already know the answer.
- Day 4: Build one of your usual reports by hand while the tool builds it too. Time both.
- Day 5: Corner your team and ask what they liked and what made them groan.
FAQs
What is insurance software development?
Put simply, it’s making software for insurance jobs like claims, policies, billing, and client portals. A claims firm can have developers build something custom, or buy a product that’s already made for claims.
How much does custom insurance software cost?
Honestly, it swings a lot. Development firms list prices starting around $120,000 for an average mobile insurance app, and the big AI systems go past $1 million. Then there’s upkeep, which sends a fresh bill every year.
How long does it take to build insurance software?
Plan on at least 3 months before anything works. Simple projects can wrap up in 3 to 6 months. Anything with AI and lots of integrations tends to run past a year.
Is a generic CRM enough for claims?
Not really. A CRM is made for contacts and sales deals. A claim needs its own file, with estimates, supplements, deadlines, and billing hanging off it.
Can claims software read Xactimate estimates?
Some can. Adjusted reads Xactimate formats natively, so you don’t retype line items before comparing estimates. Ask any vendor to prove it on one of your own files.
Bottom Line
Building feels powerful, but most claims firms don’t need a software project. What you probably need is your files, estimates, and billing in one spot. You’ve likely wanted that since last hail season.
Skip the months of planning and watch it work on a real claim instead. Book your free Adjusted demo today, and see estimate comparison, policy review, and billing sit together in one record, backed by a 30 day money back guarantee.
• Build only if your process is truly unusual.
• Buy if your needs look like most claims teams.
• Test one real claim before you decide.
