Insurance Workflow Automation: A Real Guide for Claims Professionals in 2026
If you have ever spent a Friday afternoon comparing two Xactimate estimates line by line, you already know why this topic matters to you. Most articles about insurance workflow automation are written for carriers and call centers, not for the people who actually build claim files by hand.
This guide is different. It is written for public adjusters, restoration contractors, and P&C attorneys who need automation that respects how a claim actually moves, not a generic sales pipeline dressed up in insurance language.
Automation That Fits Claims
Insurance workflow automation means using software to handle the repeatable parts of a claim, so people can spend their time on judgment calls instead of data entry. For claims professionals, the highest value use cases are estimate variance detection, policy coverage extraction, and billing tied directly to the claim record. The right tool should be built around the claim file itself, not a retrofitted sales CRM, and it should meet SOC 2 Type II standards to prove data stays secure and defensible.
What Is Insurance Workflow Automation
Insurance workflow automation is technology that takes over the repetitive steps inside a claim, things like data entry, document sorting, and status updates, so people can focus on decisions that actually require judgment. It sounds simple, and at its core it is.
Where it gets more interesting is scope. McKinsey has estimated that more than half of claims activities will shift toward automation over the next several years as AI moves the industry from reacting to problems toward predicting and preventing them. That shift is already visible in how claim files move today, one document, one estimate, one policy detail at a time.
Why Claims Professionals Need a Different Kind of Automation
Most automation content on the internet is written for insurance carriers or independent agencies. Their version of a workflow starts with a lead and ends with a renewal, which is a completely different shape than a claim file.
A claim starts with a loss, moves through documentation, estimating, and negotiation, and ends with a settlement that has to hold up if it is ever challenged. If you have looked at claims management software built specifically for that lifecycle, you already know why a relabeled sales CRM never quite fits the way your team actually works.
Where Automation Actually Saves Time on a Claim
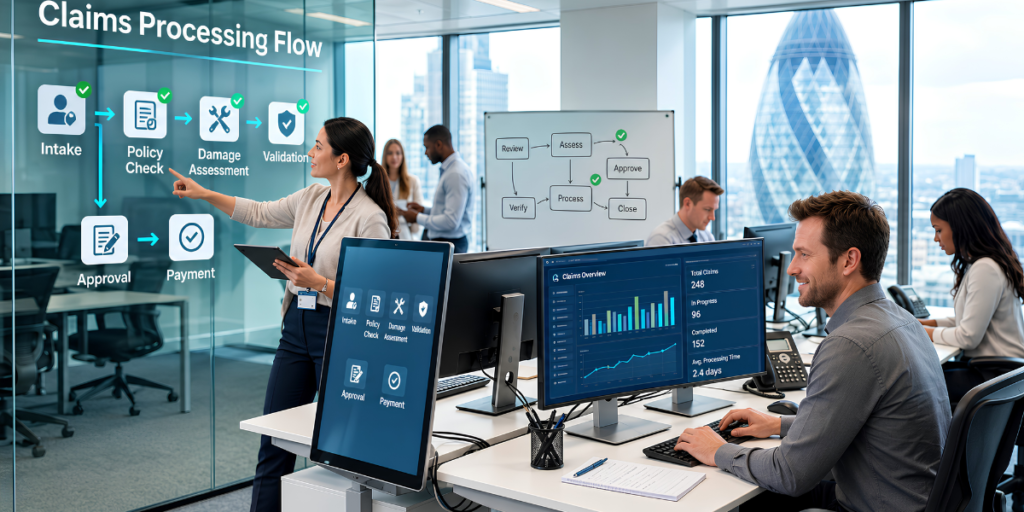
The time savings are not evenly spread across a claim file. Some tasks barely benefit from automation, while a few specific ones save hours every single week once they are handled by software instead of by hand.
Here is how the manual and automated versions of the same tasks typically compare.
| Task | Manual Approach | Automated Approach |
| Estimate variance review | Line-by-line comparison across PDFs, often by hand | Structured extraction with variances flagged automatically |
| Policy coverage lookup | Searching a scanned policy document for limits and exclusions | Coverage, limits, and exclusions surfaced instantly with source references |
| Billing and time tracking | Tracked separately from the claim in spreadsheets | Tied directly to the claim record for accuracy and faster payment |
| Document organization | Sorted manually across email, drives, and folders | Automatically filed into a single claim record |
Xactimate, Policy Data, and the Tools Behind the Automation
Two document types drive most of the manual work on a property claim, estimates and policies. Xactimate, the estimating standard used across the property claims industry, produces detailed line item data that is easy for a person to read but slow for a person to compare across versions by hand.
Automation built for claims work reads that same output and structures it instantly, pulling out RCV, ACV, depreciation, and O&P without anyone retyping a single figure. The same applies to policies, where a claim workspace that centralizes files, estimates, and coverage details turns a scanned policy into searchable, structured information in minutes instead of hours.
How to Automate Your Workflow Without Losing Control
The biggest hesitation claims professionals have about automation is losing oversight of their own files. That worry is fair, and it is worth addressing directly rather than waving away.
The way to keep control is to choose automation that shows its work. If a tool flags a variance or extracts a policy limit, it should also show exactly where that information came from, the same evidentiary discipline behind the idea that being organized is not the same thing as being defensible. Anything less becomes a liability the moment a claim is disputed.
What to Look For in Insurance Workflow Automation Software
Not every automation tool is built with claims work in mind, so the checklist for choosing one should reflect that. A few things matter more than the rest.
Look for software built around the claim record rather than a contact record, billing that ties directly to the file, and independently verified security. A SOC 2 Type II examination, the standard set by the American Institute of CPAs, is one of the clearest signals that a vendor takes sensitive claims data seriously rather than treating it as an afterthought.
The Real Cost of Staying Manual
It is easy to underestimate what manual processes cost, because the cost shows up as delay rather than as a line item. Delay is exactly what policyholders and clients feel most.
According to the J.D. Power 2026 U.S. Property Claims Satisfaction Study, the average homeowner still waits over a month for final claim payment, even after recent improvements. Every hour saved on estimate review or policy lookup is an hour that goes back into closing that gap.
See It Inside Your Own Claim Files
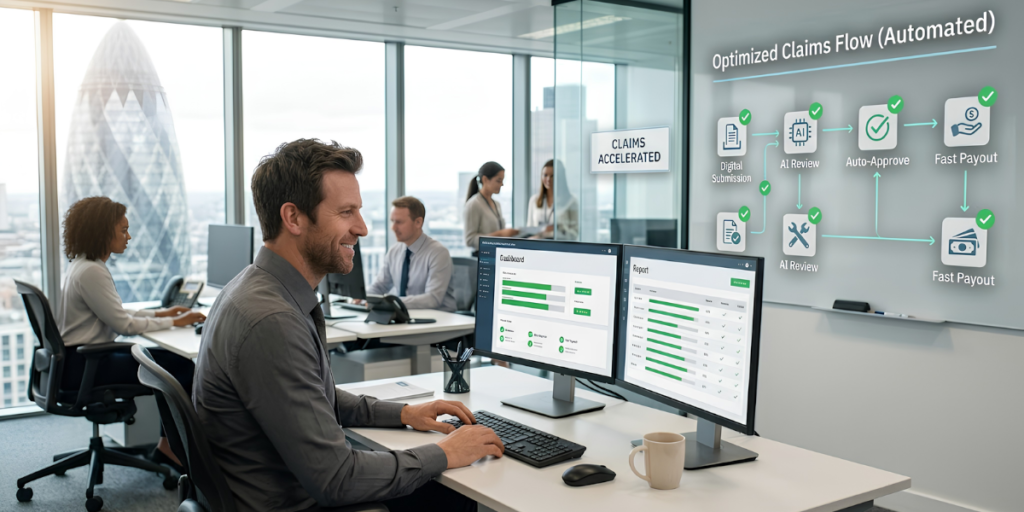
The easiest way to judge any of this is against a real file, not a demo script. If you want to see how estimate variance detection, policy extraction, and claim tied billing work together, you can book a walkthrough with your own claim data and compare it directly to how your team works today.
FAQs
Is insurance workflow automation only useful for large firms?
No. Firms with a handful of adjusters often feel the time savings the most, since there is no back office team to absorb the manual work.
Does automation replace the adjuster’s judgment?
No. It removes the repetitive steps around a claim so the adjuster can spend more time on the parts that genuinely require judgment, like strategy and negotiation.
How is this different from a generic CRM with automation features?
A generic CRM is built around contacts and deals. Claims specific automation is built around the claim file itself, including estimates, policies, and billing tied to that one file.
Is claims data safe with automation tools?
It should be. Look for independent verification like a SOC 2 Type II report rather than taking a vendor’s word for it.
Bottom Line
Insurance workflow automation is not one thing, it changes shape depending on who is using it. For claims professionals, the version that matters is built around the claim file itself, not a sales pipeline borrowed from a different industry, and that shift is exactly what Deloitte’s recent analysis of claims trends points to as well, with technology and Gen AI named as one of the biggest drivers of better claims outcomes industry wide.
Estimate variance detection, policy extraction, and claim tied billing are where the real time gets returned to your team, and the right tool will always be able to show its work when a file is challenged. If you want to see what that looks like against one of your own claim files, book a walkthrough with Adjusted and compare it directly to how your team works today.
