Cloud-Based Insurance Software: The Guide for Claims Teams
Search “cloud based insurance software” and you’ll get page after page written for insurance companies, underwriting departments, and policy admin teams. Fine if that’s you. But a huge chunk of people searching this term aren’t running a carrier, they’re running claims, and most of what’s out there wasn’t written with them in mind. This piece tries to fix that gap.
Cloud based insurance software just means the program lives on someone else’s servers instead of yours, so you log in from anywhere instead of installing it on one machine. It tends to cost less to start, scales without a hardware upgrade, and is usually locked down tighter than what a small company could build in house. Most products built around this term still target carriers and agencies though. If you’re a public adjuster, a restoration contractor, or a claims attorney, what you actually need is a bit narrower, and we’ll get to that.
What Cloud Based Insurance Software Actually Means
Strip away the marketing and it’s simple. Cloud based insurance software is any insurance program that runs on remote servers rather than a computer sitting in your office. You don’t install it, you don’t patch it, you just log in.
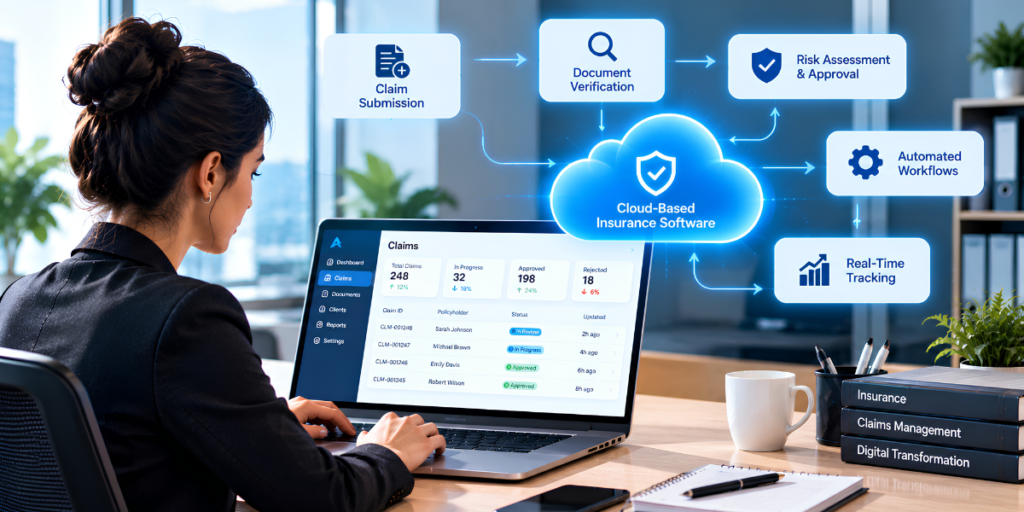
For a carrier, that usually covers policy admin, billing, and underwriting. For someone handling claims, it looks different. It’s a place to hold claim files, estimates, photos, and policy documents, and to move a file from first notice of loss through to settlement without five different apps open at once.
How It Actually Works Behind the Scenes
Your data sits on infrastructure owned by a provider like Amazon Web Services or Microsoft Azure, not on a box in a server closet. The software vendor builds on top of that, and you access the whole thing through a browser or an app.
Practically, this means updates happen without you lifting a finger, your team can log in from a job site or a laptop at home, and if your office loses power, your work is still sitting there untouched. The provider carries the weight of keeping servers patched and backed up, which is honestly a job most small firms have no business trying to do themselves.
Why Companies Keep Moving to the Cloud
The shift toward cloud isn’t a trend anymore, it’s basically finished. Datos Insights research found the share of insurers using cloud infrastructure jumped from around 70 percent in 2018 to more than 90 percent a few years later, and most of the rest were planning to catch up.
A few reasons keep coming up when you ask people why they switched.
| Benefit | What It Actually Looks Like |
| Lower cost to start | You pay a monthly fee instead of buying servers outright |
| Work from anywhere | Same data whether you’re at the office, a job site, or home |
| Updates handle themselves | New features and patches roll out without IT involvement |
| Tighter security | Providers pour more into security than most single companies can afford |
| Room to grow | Add users or storage without swapping hardware |
Cloud vs On Premise, and Why the Gap Is Widening
On premise is the old model. You buy the software, run it on your own servers, and your team keeps it alive. More control, sure, but also a bigger bill upfront and someone internally who has to babysit it.
Cloud flips that. Lower cost to get started, faster to set up, and the technical upkeep isn’t your problem anymore. Gartner research projects spending on public cloud in insurance will keep climbing sharply through the rest of the decade, which tells you where most companies have already landed on that tradeoff.
Is It Actually Secure
Fair question, especially since claim files are full of personal and financial details you really don’t want floating around. The honest answer is that a solid cloud provider usually locks things down tighter than a small company could manage on its own, because security is their entire job, not a side task.
What you want to see is a real certification, not a badge on a homepage. SOC 2 Type II, defined by the AICPA itself, means an outside firm actually reviewed the provider’s security, availability, and confidentiality controls. Adjusted publishes its own SOC 2 Type II report so you can check the details yourself instead of taking anyone’s word for it.
Where Generic Cloud Insurance Software Falls Short for Claims Work
This is usually where articles like this one stop, but it’s exactly where the real problem starts if claims are your job. Generic cloud insurance software was built for carriers managing policies and premiums. It was never built around the day to day mess of an active claim file.
A public adjuster, a restoration contractor, or a P&C attorney is fighting a different battle entirely, and it deserves software built for that battle specifically, not a repurposed sales CRM with an insurance label taped on. McKinsey’s research on cloud in insurance even points out that most insurers still underestimate what cloud can do, and that gap is even wider once you leave the carrier side entirely.
What Claims Professionals Actually Need From Their Software
If you work claims for a living, your headaches are specific, not generic. You need something that reads an Xactimate estimate and pulls out RCV, ACV, and depreciation numbers without you retyping them by hand. You need billing tied directly to each claim, not bolted on as an afterthought. And you need every photo, email, and document sitting inside the right claim automatically, instead of scattered across an inbox and a shared drive somewhere.
This isn’t a niche complaint either. Organizations like the National Association of Public Insurance Adjusters exist partly because this work runs on its own rhythm, one that a typical agency management system was never designed around.
What This Software Tends to Cost
Pricing swings a lot depending on what you actually need. A lean setup for a small team might land at a few hundred dollars a month, while a fuller platform with extras like e-signature or analytics can run into the low thousands depending on how many people are using it.
Honestly, the subscription price usually isn’t the real cost. The real cost shows up in the hours your team burns re-keying data because the software doesn’t fit how claims actually move. Save your team even a few hours a week and the thing pays for itself fast.
Picking the Right Platform for Your Team
Start with how your claims actually move, not a list of features a salesperson hands you. Does it read Xactimate files natively? Does billing live inside each claim rather than a separate tab? Does it actually understand the claim lifecycle, or is it a generic CRM wearing an insurance costume?
If you want to see how a claims-first platform handles this differently, our breakdown of what to look for in claims management software walks through the specifics most buyers miss.
FAQs
Is cloud based insurance software the same thing as claims management software?
Not quite. Cloud based insurance software is the broad umbrella, it can mean policy admin and billing for a carrier. Claims management software is narrower, built specifically around running a claim file start to finish.
Do I need an IT person to run cloud software?
No, and that’s kind of the point. The provider handles servers, updates, and security, so your team doesn’t need in house IT just to keep the lights on.
Can claims software actually read Xactimate estimates?
Some platforms built specifically for claims professionals can pull structured data straight out of an Xactimate PDF, no manual re-typing required.
Is moving from on premise to cloud a headache?
Usually not with a decent provider. Most will handle the data migration as part of onboarding rather than leaving you to sort it out alone.
How do I check if a provider’s security claims are actually real?
Ask for the SOC 2 Type II report itself, not just a logo on their site. If they can’t produce it, that tells you something.
Bottom Line
Cloud based insurance software has become the default for good reason, it’s cheaper to start, easier to scale, and generally locked down better than most companies could manage alone. But if claims are what you actually do all day, a platform built for carriers will always feel a little off, because it was never built with your workflow in mind.
Ready to see what claims-first software actually feels like day to day? Explore Adjusted’s pricing and get started, no setup fees, no long contract, just software built around the claim itself.
