Insurance Operations Software: Pick One You’ll Actually Keep
What Is Insurance Operations Software?
TLDR: Insurance operations software is basically one folder for a claim’s files, estimates, tasks, and bills.
Google insurance operations software and nearly every page you get is about carriers. They talk about underwriting, policy billing, and renewals. That doesn’t do much for a public adjuster, a restoration contractor, or a claims attorney. You run operations too. You just do it on the other side of the claim.
In plain terms, it’s what you run a claim in, from the first phone call right through to the last payment. The estimate, the emails, the deadline list, and the invoices all sit in that one file. It’s not the same thing as policy administration software, which runs a policy for an insurer. We broke that down in policy administration versus claims management software, and it’s worth a read if the two still sound alike.
Why Claims Work Gets Messy So Fast
Think about how a claim really goes. You get photos from the site visit. The carrier sends an estimate. Then a supplement shows up, and then another one. Somebody scans the policy. Emails stack up. The contractor’s invoice shows up in a separate thread. None of it ends up in the same place. Half of it is on somebody’s phone, and the rest is in a drive folder or a spreadsheet only one person understands. Then the carrier calls and you have to stop everything and dig.
That digging has a real cost. Here is what J.D. Power found in the 2026 U.S. Property Claims Satisfaction Study, which surveyed 5,093 homeowners who had filed a claim. Satisfaction averaged 702 out of 1,000, up 20 points. Repairs took 29.6 days on average, and final payment took 40.7 days. The thing customers cared about most was a fair settlement. About a third also said their policy didn’t work the way they expected, and a lack of explanation was a common complaint. It’s a lot easier to explain things when your file is in order.
You might need a better setup if:
- You search more than one place for the same email
- Deadlines live in somebody’s notes app
- Only one person knows where things are saved
Features That Actually Matter
Most feature lists are long. Only a handful make a real difference day to day.
Claim Workspace and Document Control
Every claim needs one home. I’d want the whole story in one file, meaning emails, photos, notes, and every version of the estimate. That way somebody covering for you can read the file instead of phoning you on vacation. Photo search is worth testing in a demo. Some claims end up with hundreds of photos, and renaming them one by one is miserable. Adjusted handles this by letting you describe the photo you’re after, so nobody has to tag anything.
- One file per claim, not one folder per tool
- Search that covers photos and documents
- Permissions for staff, partners, and clients
Estimate and Policy Review
Lining up a carrier’s estimate against your supplement, line by line, takes forever. So does reading a long policy to find the one endorsement that matters. Adjusted’s Estimate Analyzer reads Xactimate files and compares the two estimates using AI. The policy tools pull out coverage language so you can check it quickly. You’d still check the results yourself, of course. It’s just faster to start from a list of differences than from nothing.
Billing, Tasks, and Reporting
Billing should live inside the claim. Tie every invoice, time entry, and lien back to the claim it came from, and you always know what’s owed. You can also show how you got to that number. For deadlines, you want reminders and a calendar everyone can see. A report or two helps you catch the claims that have quietly stalled.
- Invoices tied to the claim they belong to
- Reminders that go off before a deadline
- Reports on cycle time and open balances
Where AI Helps and Where It Shouldn’t
AI is good at reading. It can skim a 40 page policy, point out a page that’s missing, and show what changed between two estimates, all in a few seconds. What it shouldn’t do is make the call. A coverage opinion, a negotiating position, or a figure headed to a carrier should get a human check first. I think of it as a quick new hire who’s still learning your files. It’s helpful, but you still review the work.
Regulators are thinking along the same lines. The NAIC adopted a model bulletin on how insurers use AI back in December 2023, and NAIC’s state adoption map shows which states have picked it up. The NIST AI Risk Management Framework is another useful reference on keeping AI in check. None of it applies to you directly. What it does tell you is that carriers are expected to explain how they use AI. It’s fair to ask your own software vendor for the same.
- AI can sum up a policy, compare two estimates, or find a photo
- You still handle coverage opinions, negotiation, final numbers, and client advice
Who Benefits Most from Insurance Operations Software
Each group gets something a little different out of it.
Public Adjusters
Plenty of public adjusters work on contingency, so an hour lost digging for a document doesn’t pay anything. One organized record and faster estimate checks let you take on more files without hiring. Fee tracking on each claim is a nice bonus too.
Restoration Contractors
For a contractor, the stress is mostly about collecting. If the invoices, liens, and hours are tied to the claim, you’ve got an answer ready when somebody disputes a bill. And the office and the crew in the field see the same information, not two different spreadsheets.
Claims Attorneys
A lawyer needs a file that can take a hit when the other side comes at it. Having the documents, policy language, and letters in one spot means a paralegal isn’t stuck sorting them all day. A history of who opened or changed what comes in handy too, especially with privileged material. Security matters a lot here.
How to Choose the Right Platform
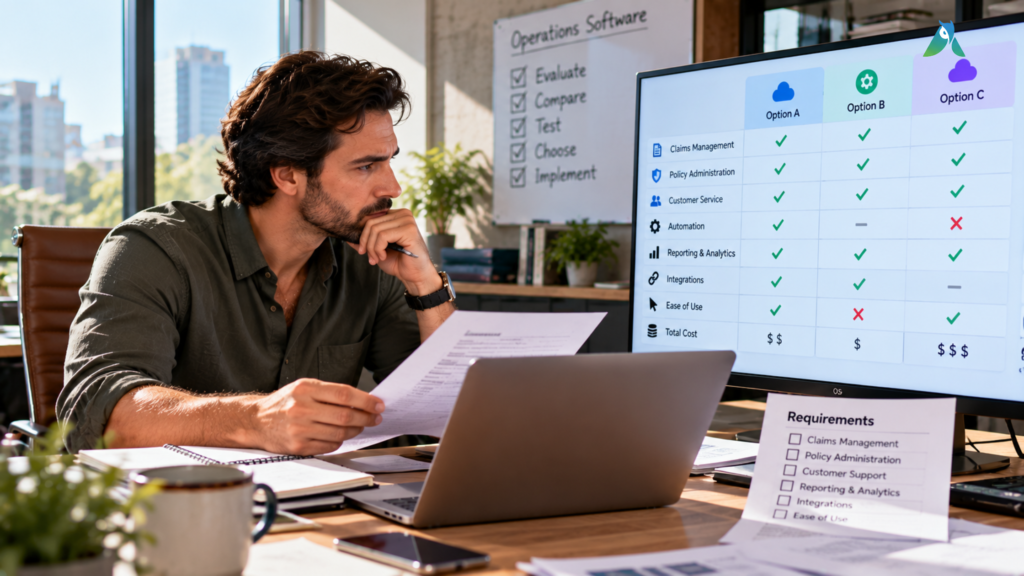
A checklist won’t tell vendors apart, since they all say yes. Tougher questions work better. Here’s a table you can take into a demo.
| Question to ask | A good answer | A red flag |
| Is it built for claims? | Yes, with claim lifecycle, estimates, and policy review built in | It’s a sales CRM with a few claim terms added |
| How does the AI work? | It flags things and a person confirms them | You can’t see where an answer came from |
| Where does billing live? | Inside each claim | In a separate tool you match up by hand |
| How do you prove security? | An audit report I can actually read | Just a promise and a padlock icon |
| How do we move our files? | A clear plan and real help | “Export a spreadsheet and start fresh” |
| What does it connect to? | Integrations that work today | Features marked “coming soon” |
These files hold names, addresses, and money details, so don’t skip the security talk. The thing to ask for is a SOC 2 Type II report. In a nutshell, an auditor checks the vendor’s controls against the AICPA Trust Services Criteria, and the checking happens over a stretch of time rather than on one day. Look at what’s covered and make sure the report is recent. Adjusted’s site says a licensed CPA firm looked at its security, availability, and confidentiality controls.
How to Switch Without Chaos
Nobody enjoys changing software mid season, and your open claims keep moving while you do it. Resist the urge to move it all in one go. Take a few weeks and do it in stages. A frantic weekend of copying files is how things go missing.
- Make a quick list of open claims, key contacts, and any document you can’t afford to lose
- Move closed files first, since nothing is urgent there
- Start every new claim in the new system
- Move active files in small groups and double check each group before the next
It also pays to know what support the vendor offers while you’re moving. Adjusted offers onboarding and migration support built for this step by step approach, and good support can make the first month a lot easier.
FAQs
So what exactly is insurance operations software?
It’s software for running the day to day work on a claim. Everything from the estimates to the billing lives in one file. People in this line of work use it instead of juggling inboxes, drives, and spreadsheets.
How is it different from claims management software?
Not by much. Insurance operations software is the bigger label. Claims management software tends to mean the version made for the people handling claims.
Is AI any good at reading a policy?
Usually, as long as the document is readable. It finds coverage language fast and flags what looks missing. Fuzzy scans can throw it off, so anything important should be checked against the original.
What does Type II mean on a SOC 2 report?
An independent accountant, not the vendor, tested the security controls over a stretch of time and reported the results. A Type I report only looks at the design at one moment, so Type II tells you more.
Will it replace my CRM?
For claim work, often yes. A typical CRM is designed around sales, not claims. So documents, estimates, and billing tend to end up in other tools.
Tied to switching without risk
You already know how to work a claim. It’s the paperwork around it that wears you down. Good insurance operations software puts all of that in one place, so you spend more time on the parts that need your brain. Want to see how it handles your files? Book your Adjusted demo today and see a full claim record in action.
Before you decide, run one open claim through a live demo. Check how it compares two estimates, how it searches photos, and whether the billing ties back to the claim.
